Shipping Home & Kitchen Products from China to the UK: Planning an Emergency Air Restock
Use air express only when the lost-sales cost of a stockout exceeds the air premium over ocean. Air carriers charge on chargeable weight — the greater of actual and volumetric (1 CBM ≈ 167 kg) — so densify cartons to cut volume. For the UK, secure a GB EORI, classify under the UK Integrated Online Tariff, and use postponed import VAT so cash isn't tied at the border. Decision rule: ship by air if (margin × units-at-risk) > air premium. Milestones: ready → pickup → flight → clearance → delivery. Next action: collect carton dims/weights + HS codes.
- Air wins only when lost sales from a stockout beat the air-versus-ocean premium; otherwise ocean LCL is the cheaper plan.6
- Air is billed on chargeable weight (actual vs volumetric at 1 CBM ≈ 167 kg); dense, small cartons protect your margin.
- Secure a GB EORI and classify each SKU under the UK Integrated Online Tariff before you book the flight.12
- Use postponed import VAT to keep working capital off the border; missing it ties cash in duty and VAT at clearance.4
- Five-to-ten days is a planning window, not a guarantee; confirm the flight slot and clearance before you promise a shelf date.3
On this page
When does air express beat ocean for an urgent UK restock?
Air express earns its premium only when the cost of being out of stock in the UK exceeds the extra freight you pay over ocean. A home & kitchen seller facing a stockout during a peak window — a new Amazon listing gaining traction, a Q4 gift promotion, or a retailer refill that misses a delivery deadline — should compare the lost contribution margin on the units-at-risk against the air surcharge. If (margin × units-at-risk) is larger than the air premium, fly the cartons; if not, ocean LCL is the cheaper plan and the stockout is the lesser loss.
This is a planning decision, not a guarantee of a fixed transit day. The buyer is usually a UK marketplace seller, a DTC brand, or a distributor topping up a fast-selling SKU such as a small appliance, a cookware set or a kitchen gadget. Air works when the parcel is small, dense and high-value per kilo; it fails when you air-freight a bulky, low-margin item that ocean would have carried for a fraction. Set the trigger before the stockout, because booking under pressure is where premiums get accepted without a check. The Incoterm you choose also moves who carries risk and cost across the flight and clearance.6
Ship by air only when (margin × units-at-risk) > (air cost − ocean cost). Below that line, plan ocean and accept the slower window.
Chargeable weight: actual versus volumetric, and the 1 CBM ≈ 167 kg rule
Air freight is never billed on gross weight alone. The carrier charges the greater of actual (scale) weight and volumetric weight, then rounds up to the next 0.5 kg. Volumetric weight is length × width × height in centimetres divided by 6,000 — the IATA divisor — and 1 CBM works out to about 167 kg. A carton of light, bulky packaging therefore pays on its volume, not its scale weight, which is the trap for home & kitchen goods that ship in oversized boxes with air pillows inside.
Densify before you book: smaller cartons, less void fill, and combining accessories into one box cuts the volumetric figure and can drop the chargeable weight by a full step. A 0.5 CBM carton of 40 kg of gadgets bills at roughly 83 kg volumetric, so you pay for air you didn't need. Re-pack to remove the dead space and the same goods may bill near their 40 kg actual. The chargeable weight guide shows the divisor math; the CBM calculator converts packed sizes into both CBM and volumetric kilograms so you can quote on the right number.
Airport-to-airport versus door-to-door
Airport-to-airport quotes look cheap because they exclude UK collection, destination handling, clearance and final-mile; door-to-door folds those in but hides the breakdown. Quote both on the same scope so the comparison is real, and confirm whether the rate is chargeable-weight or a flat per-kg plus minimum charge.
Cost composition: freight plus fuel, security, UK duty and VAT
An air restock quote to the UK is built from several lines, and the freight is only part of it. Expect the airline base rate on chargeable weight, a fuel surcharge that moves with oil, a security surcharge per shipment or per kg, and possibly a peak-season or handling fee at the origin station. On arrival, UK cost lines are the import duty set by the commodity code and the import VAT on the duty-inclusive value. Under DAP or DDP the seller pre-pays these; under FOB/CFR/CPT the UK buyer settles them at clearance, so the Incoterm decides who writes the cheque.6
Do not treat the airline rate as the landed cost. A 120 kg chargeable-weight shipment at a given per-kg rate can look attractive until the fuel and security surcharges, the destination handling, the broker fee, the UK duty and the 20% import VAT are added. UK duty rates vary widely by HS code — many small appliances and cookware sit under mid-single-digit percentages, while some finished goods are higher — so classify first, then cost. Use postponed import VAT accounting so the 20% is not a cash outflow at the border.4
| Cost line | Air Express (per 0.6 CBM / 120 kg chg wt) | Ocean LCL (per 0.6 CBM) | Difference driver |
|---|---|---|---|
| Origin cartage and export handling | 120 | 110 | Similar pickup and docs. |
| Main carriage (airline vs ocean) | 1,450 | 240 | Air premium is the biggest gap. |
| Fuel / security surcharge | 180 | 0 (ocean bunker built in) | Air adds explicit surcharges. |
| UK destination handling and clearance | 160 | 130 | Both need entry and handling. |
| UK import duty (classified HS) | 60 | 60 | Same scope, same tariff. |
| UK import VAT (postponed) | 0 cash at border | 0 cash at border | PVA removes the cash tie-up. |
| Inland delivery to UK warehouse | 95 | 110 | Comparable final-mile. |
| Total, duty/VAT excluded from cash | 2,065 | 650 | Air premium ≈ 1,415 on this scope. |
Table 1 is an Illustrative Calculation with stated assumptions, not a tariff, quotation or live rate. Airline, fuel and duty figures change; confirm a current quote and the current UK tariff before booking.2
EORI and UK Integrated Online Tariff classification
Before any flight is booked, the UK importer of record needs a GB-prefixed EORI number; without it, customs cannot process the entry and the goods stall at clearance. A GB EORI covers England, Wales and Scotland, while Northern Ireland movements may need an XI EORI, so confirm which applies to your delivery address. Apply for it early because clearance cannot start without it, and a missing EORI is the most common avoidable air-delay.1
Each SKU must be classified under the UK Integrated Online Tariff to set the duty rate, the import VAT base and any control or licence. A toaster, a knife block and a ceramic baking dish sit under different commodity codes with different rates and documents, so classify per item, not per shipment. Commodity codes and rates change with trade dates, so verify the current code on the official tariff before you book and keep the code in the data pack.2 The nine-step import workflow sets out EORI, commodity code, declarant, valuation, licences, labelling, declaration and C79 recovery in order.3
Use postponed import VAT so cash isn't tied up at the border
UK import VAT is 20% of the duty-inclusive value and is normally due at clearance. Postponed VAT accounting (PVA) lets a VAT-registered UK importer account for both the due and the recoverable import VAT on the same VAT return, so no cash leaves the business at the border and no refund wait follows. For a fast restock this keeps working capital free to buy the next batch rather than parking it in a border payment.
PVA is an election on the import declaration, not an automatic setting, and it requires the importer to be VAT-registered and to record the figures from the monthly C79 or online statement. If you skip it, the courier or broker pays the VAT and recharges you, which ties cash and adds a handling fee. Confirm with your customs agent that PVA is selected before the flight departs, and reconcile the statement each period.4
UKCA marking where relevant for appliances and gadgets
Many home & kitchen electricals — a blender, a coffee machine, a heated gadget — need conformity marking to enter Great Britain. CE is still recognised under the current GB framework, but UKCA is the domestic mark and responsible persons, importers and distributors each carry defined duties, so confirm which mark your SKU carries and whether the documentation supports it before air-freighting a batch that could be challenged at the border.5
Marking is not a shipping step but a market-access gate that an air restock can trip over if ignored. Keep the declaration of conformity, test reports and the authorised representative details in the data pack alongside the HS code, because a clearance hold on compliance costs the very speed you paid air freight to gain. Non-electrical cookware and textiles are usually outside UKCA scope, but any product with a plug, a motor or a heating element should be checked.
Packaging for air: light, protective, no loose bits
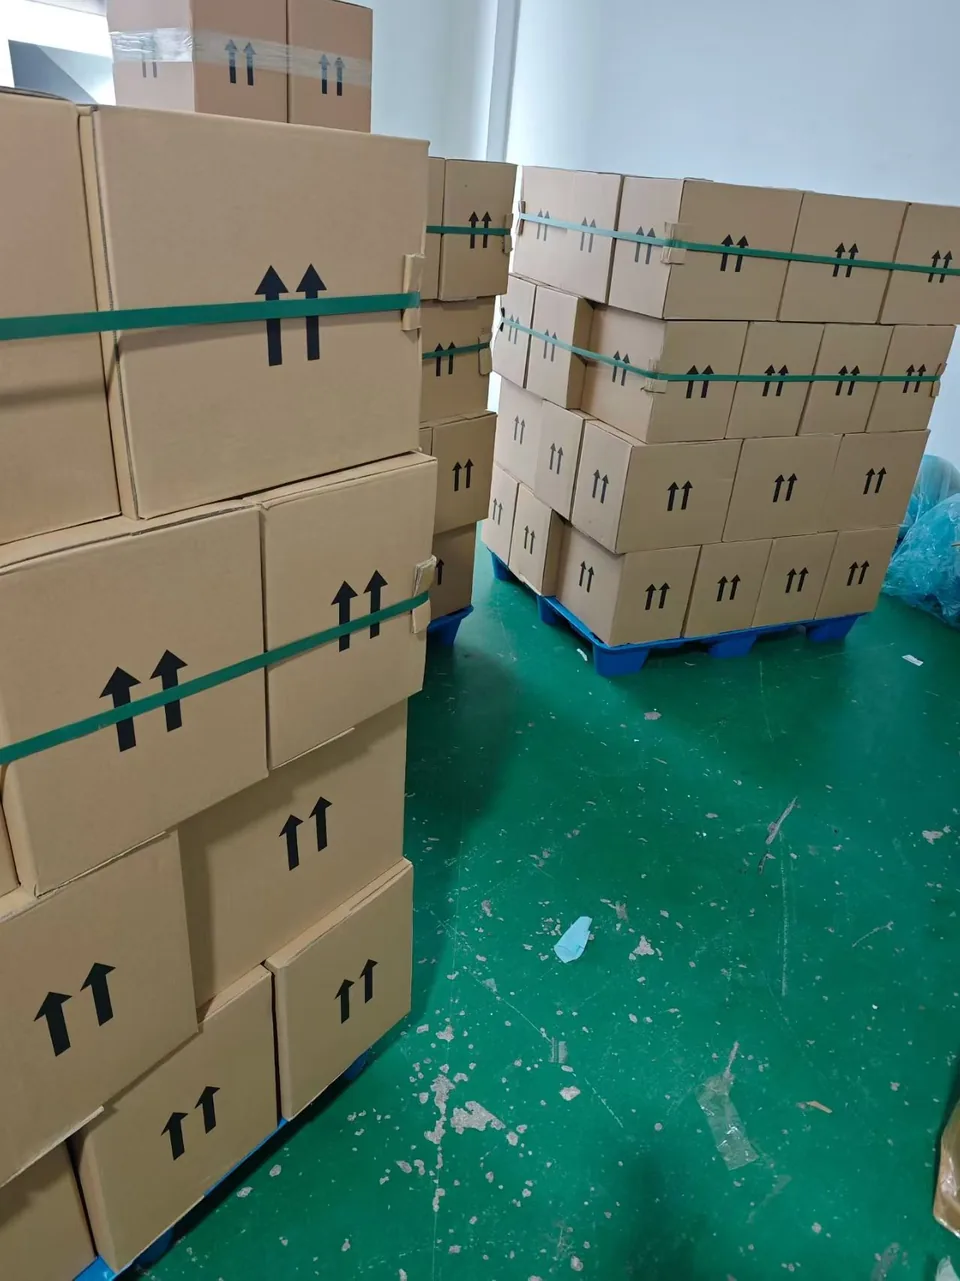
Air handling is rougher on individual cartons than sealed ocean containers, and every gram of packaging is paid as chargeable weight, so pack to be light and tight. Use double-wall cartons sized to the product with minimal void fill, internal dividers instead of loose air pillows, and tape that survives the cold-chain hold of an aircraft belly. Loose inserts fall out during screening and add volume that you pay for, so build protection into the carton wall.
Battery rules decide whether a small appliance can fly at all: loose or fitted lithium cells must meet the IATA dangerous-goods provisions, and some configurations need declaration or cannot travel in passenger aircraft holds. Confirm the battery status of every SKU before booking, because a single non-compliant carton can hold the whole consolidation. Photograph the packed carton and the marks so the data pack matches the physical load.
Stack and label for screening
Keep cartons uniform so they stack in the air freight build-up, label each with the HAWB, piece count and a clear shipper-consignee, and mark any orientation or battery handling. A clean, scannable carton moves through screening faster and avoids manual inspection that costs a day.
Emergency timeline: a 5–10 day plan from ready to shelf
Treat five to ten days as a planning window for an air restock to a UK warehouse, not a committed delivery date. Day 0–1 is supplier readiness and pickup; day 1–2 the freight forwarder builds the shipment, files the HAWB and tenders to the airline; day 2–5 is the flight plus UK arrival and clearance; day 5–7 is destination handling and delivery; day 7–10 is buffer for inspection, address correction or a missed consolidation. Coastal hubs and a clean PVA entry compress the window; a missing EORI or a compliance query extends it.
The timeline is owned by the sequence, not by hope. Lock the ready date, confirm a flight slot rather than space-available, pre-lodge the entry with the EORI and HS codes, and brief the UK warehouse on the arrival so the final-mile is booked. A promised shelf date should sit inside the 5–10 day range with buffer, and anything tighter needs a confirmed express product, not a standard air consolidation.3
- Supplier confirms ready date and sends packed dims, weights, carton count and HS codes.
- Forwarder books a confirmed flight slot and issues the HAWB; you confirm chargeable weight.
- UK importer confirms GB EORI, PVA election and classified HS codes in the entry.14
- Cartons tender to the airline, fly, and arrive at the UK gateway for clearance.
- Broker clears under PVA, destination handling releases, and final-mile delivers to the warehouse.3
Quote checklist for an air restock to the UK
Send one complete data pack so the quote matches the load that actually flies. A quote built on estimates is revised upward at clearance, which defeats the urgency. The forwarder can only price chargeable weight, choose a flight and plan UK delivery when carton detail, HS codes and address access arrive together; anything missing reappears as a surcharge or a hold.
Ask for packed dimensions after cartons are sealed, not catalogue sizes, and insist the quote state airport-to-airport versus door-to-door and whether it is chargeable-weight or flat-rate with a minimum. Cross-check the duty and VAT lines against your HS codes and confirm PVA is included so the cash impact is honest.24
- Packed carton dimensions per SKU, carton count and total actual gross weight in kilograms.
- Per-carton and total volumetric weight, and which figure is chargeable (the greater of the two).
- Six-digit HS codes per SKU, invoice values and country of origin for tariff and duty.
- GB EORI number, PVA election and the named UK importer of record and declarant.
- Battery status of every SKU and any UKCA or conformity documentation for electricals.5
- Ready date, origin pickup address, chosen Incoterm and required UK delivery date.
- Exact UK delivery address, dock or tail-lift access, receiving hours and contact.
Common mistakes: ignoring chargeable weight, cash tied in VAT, missing EORI
The recurring air-restock failures are quoting and paperwork errors made before the cargo moves, not airline slips. Lock the data pack, the HS codes and the VAT election at the purchase-order stage and re-confirm them at the ready date. Each issue below has a cheap fix at booking and an expensive one at the border.
- Quoting on gross weight and ignoring volumetric: re-pack and quote on chargeable weight, the greater of actual and volumetric.
- Letting import VAT become a cash outflow: elect PVA so the 20% is accounted, not paid, at the border.4
- Booking without a GB EORI: apply early; a missing EORI stalls clearance and burns the air premium.1
- Classifying the whole shipment as one code: classify per SKU, since appliances, cookware and ceramics differ.2
- Assuming CE removes UKCA duties: confirm the mark and responsible-person paperwork for electricals.5
- Promising a shelf date tighter than 5–10 days on standard air: confirm an express product or add buffer.3
If factory, forwarder and broker hold different carton lists or HS sets, the HAWB and entry disagree and cause holds. Name one owner for the data pack.
Illustrative chargeable-weight and cost build-up
As an Illustrative Calculation, a 0.6 CBM restock of 120 kg of small kitchen gadgets from a Shenzhen supplier to a UK 3PL shows why volumetric weight drives the bill. Assumptions: cartons 120 × 40 × 30 cm, 25 cartons, 0.144 CBM and 4.8 kg each, 0.6 CBM total, 120 kg actual, GBP, 2026 planning assumptions, PVA elected, duty excluded from cash, no live rates. Verify a current quote before booking.
Volumetric weight per carton is 120 × 40 × 30 ÷ 6,000 = 24 kg, against 4.8 kg actual, so each carton bills at 24 kg and the shipment chargeable weight is 25 × 24 = 600 kg, not the 120 kg on the scale. That fivefold gap is the cost of shipping air; re-packing two gadgets per carton would roughly halve it. Here is the same movement costed against the earlier scope so the air premium is visible against ocean.
| Measure | Per carton | Total (25 cartons) | Billed as |
|---|---|---|---|
| Actual gross weight | 4.8 kg | 120 kg | Not the billing basis. |
| Volumetric weight (÷ 6,000) | 24 kg | 600 kg | Chargeable weight. |
| Chargeable weight billed | 24 kg | 600 kg | Greater of actual vs volumetric. |
| CBM equivalent (÷ 167) | 0.144 CBM | 0.6 CBM | 1 CBM ≈ 167 kg check. |
| Illustrative airline + surcharges (GBP) | — | 1,630 | On 600 kg chargeable. |
| UK handling, clearance, PVA VAT (cash 0) | — | 255 | Duty excluded from cash. |
| Total cash at border (PVA) | — | 0 | VAT postponed, not paid. |
Table 2 is an Illustrative Calculation with stated assumptions, not a live rate or quotation. Airline and surcharge figures change; confirm a current quote and the current UK tariff before booking.2
Frequently asked questions
When should I choose air over ocean for a UK home & kitchen restock?
How is chargeable weight calculated for air freight from China to the UK?
Do I need an EORI number to air-freight goods into the UK?
Can I avoid paying UK import VAT in cash at the border?
Do home & kitchen electricals need UKCA marking to enter Great Britain?
How long does an emergency air restock from China to the UK take?
How do I classify home & kitchen goods for UK duty?
What does an air restock to the UK actually cost beyond the freight rate?
Sources & References
- GOV.UK/HMRC — Get an EORI number
- GOV.UK — Find commodity codes, import duties, taxes and controls
- GOV.UK/HMRC — Import goods into the UK: step by step
- HMRC — Check when you can account for import VAT on your VAT Return
- GOV.UK — Placing UKCA or CE marked products on the market in Great Britain
- ICC — Incoterms 2020